Chapter 7 vs. Chapter 13 Bankruptcy: Means Test Calculations and Exempt Property Limits
An evidence-based comparison of debtor eligibility, means test expense deductions, property exemption limits, and debt restructuring mechanics under federal bankruptcy law.
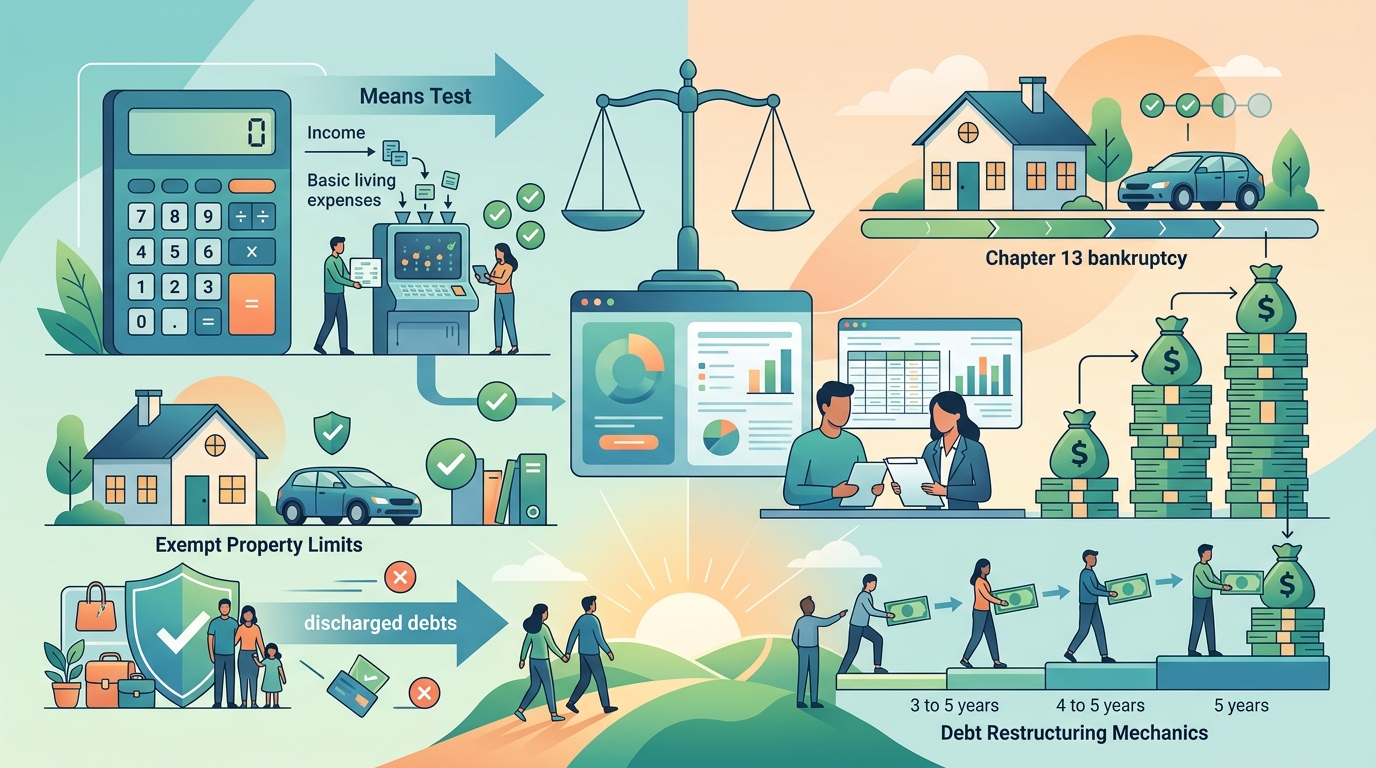
Individuals dealing with overwhelming personal debt often evaluate federal bankruptcy options to manage or resolve their financial obligations (Source 1, Source 3). Federal law provides distinct legal mechanisms for personal insolvency, primarily governed by Chapter 7 and Chapter 13 of the United States Bankruptcy Code (Source 1). Chapter 7 functions as a liquidation proceeding where non-exempt assets are converted to cash to pay creditors before remaining qualifying debts are discharged (Source 1). Chapter 13 operates as a reorganization framework, establishing a court-supervised repayment plan over three to five years (Source 1, Source 3). Determining which chapter applies depends on income evaluations, expense guidelines, asset values, and statutory debt limits (Source 1, Source 2).
Understanding the Core Structural Differences
The fundamental difference between Chapter 7 and Chapter 13 lies in how property and ongoing earnings are treated under federal law (Source 1). In a Chapter 7 filing, a court-appointed bankruptcy trustee collects non-exempt assets, liquidates them, and distributes the proceeds to unsecured creditors according to statutory priorities (Source 1). Debtors with minimal non-exempt assets—often referred to as 'no-asset cases'—can obtain a discharge without losing basic personal belongings (Source 1). The entire Chapter 7 process typically resolves within three to six months (Source 1).
Conversely, Chapter 13 allows individuals with regular income to retain their property, including non-exempt equity, by making structured monthly payments to an assigned trustee (Source 1, Source 3). The trustee distributes these funds to creditors based on a plan confirmed by the bankruptcy judge (Source 1). Chapter 13 filings are commonly utilized by homeowners seeking to cure delinquent mortgage payments or individuals whose income exceeds eligibility thresholds for Chapter 7 relief (Source 1, Source 2).
The Chapter 7 Means Test: Income Standards and State Medians
Eligibility for Chapter 7 relief is governed by the statutory means test introduced under the Bankruptcy Abuse Prevention and Consumer Protection Act (Source 2). The means test evaluates whether a debtor has sufficient disposable income to pay a portion of unsecured debts (Source 2). The initial evaluation involves calculating the debtor's Current Monthly Income (CMI), defined as the average monthly gross income received from all sources during the six full calendar months preceding the filing date (Source 1, Source 2).
CMI excludes Social Security benefits and certain disaster relief payments under federal guidelines (Source 2). The calculated annualized income (CMI multiplied by 12) is compared directly against the median household income for a family of equal size in the debtor's state of residence (Source 2). State median income figures are updated periodically by the U.S. Census Bureau and published by the U.S. Trustee Program (Source 2).
- Below-Median Household Income: If the debtor's annualized CMI is equal to or less than the state median income for their household size, the debtor passes the means test automatically and qualifies to file under Chapter 7 (Source 2).
- Above-Median Household Income: If the debtor's annualized CMI exceeds the state median income, the debtor must complete the second part of the means test calculation to evaluate allowable expense deductions (Source 2).
Allowed Monthly Expense Deductions in Means Testing
For above-median income debtors, the means test requires subtracting standardized living expenses and specific actual expenses from CMI to determine net disposable income (Source 2). Standardized expense deductions are derived from Internal Revenue Service (IRS) Financial Analysis Handbook guidelines, adapted for bankruptcy proceedings by the Executive Office for United States Trustees (Source 2).
Expense deductions fall into distinct categories established by federal standard guidelines:
- IRS National Standards: Standard allowances covering food, clothing, household supplies, personal care, and miscellaneous expenses, scaled by household size (Source 2).
- IRS Local Standards: Geographic allowances for housing, utilities, and transportation expenses based on county and metropolitan statistical area data (Source 2).
- Other Necessary Expenses: Actual out-of-pocket expenses for mandatory payroll deductions (taxes, Union dues), health insurance premiums, term life insurance, dependent care, and court-ordered obligations such as child support or alimony (Source 1, Source 2).
- Secured and Priority Debt Payments: Contractually due monthly payments on secured claims (e.g., home mortgages, vehicle loans) and past-due domestic support obligations averaged over a 60-month period (Source 2).
After subtracting allowed deductions from CMI, the remaining total represents the debtor's projected 60-month disposable income (Source 2). If this projected disposable income falls below statutory federal thresholds, the debtor passes the means test (Source 2). If disposable income exceeds these thresholds, a presumption of abuse arises, meaning the case may be dismissed or converted to a Chapter 13 reorganization (Source 1, Source 2).
Property Preservation and Bankruptcy Exempt Property Limits
A primary concern for debtors considering bankruptcy is property retention. Federal law establishes statutory exemptions that safeguard specific types and values of property from liquidation in Chapter 7 or from mandatory asset value calculations in Chapter 13 (Source 1).
Depending on state jurisdiction, debtors may choose between the federal exemption scheme set forth in Section 522 of the Bankruptcy Code or their state's statutory exemption list (Source 1). Some states require residents to use state-specific exemptions ('opt-out' states), while other states permit debtors to select whichever system provides greater protection (Source 1).
- Homestead Exemption: Protects equity in a primary residence. Federal and state codes set explicit statutory limits on equity amounts that can be exempted from bankruptcy administration (Source 1).
- Vehicle Exemption: Safeguards a specified amount of equity in motor vehicles used for personal transportation (Source 1).
- Personal Property Exemptions: Protects household goods, furnishings, wearing apparel, appliances, and tools of the trade up to specific aggregate dollar limits (Source 1).
- Wildcard Exemption: Allows debtors to apply an unallocated statutory allowance toward any asset, such as cash balances, tax refunds, or real estate equity (Source 1).
Equity is calculated by subtracting valid outstanding liens (mortgages, vehicle loans) from the item's current fair market value (Source 1). If an asset's equity is fully covered by applicable exemptions, the trustee cannot liquidate it in Chapter 7 (Source 1). In Chapter 13, non-exempt asset equity sets the 'liquidation test' baseline: unsecured creditors must receive at least as much under the Chapter 13 repayment plan as they would have received if the non-exempt property had been liquidated under Chapter 7 (Source 1).
Comparative Overview: Chapter 7 vs. Chapter 13 Parameters
| Feature | Chapter 7 Bankruptcy | Chapter 13 Bankruptcy |
|---|---|---|
| Primary Purpose | Liquidation of non-exempt assets to eliminate qualifying debts (Source 1). | Reorganization and adjustment of debts for individuals with regular income (Source 1). |
| Eligibility Requirement | Must pass the Means Test based on state median income and allowed expenses (Source 2). | Must have regular income and total debt within federal statutory debt limits (Source 1). |
| Asset Treatment | Non-exempt assets may be sold by the trustee to pay creditors (Source 1). | Debtor retains property; pays equivalent value of non-exempt equity via plan (Source 1). |
| Typical Duration | Generally 3 to 6 months from filing to debt discharge (Source 1). | Repayment plan runs 3 to 5 years (36 to 60 months) (Source 1). |
| Mortgage Arrears | Does not provide a mechanism to catch up missed payments while keeping property (Source 1). | Allows debtor to cure mortgage default over the life of the plan (Source 1). |
Structure of Chapter 13 Repayment Plan Rules
Chapter 13 operates via a repayment plan submitted by the debtor for court approval (Source 1). The plan outlines regular monthly disbursements to the standing trustee, who distributes funds among classes of creditors according to statutory priority rules (Source 1).
Plan duration is dictated by the debtor's income level relative to the state median (Source 1):
- Three-Year Plan (36 Months): Applicable when the debtor's CMI is below the state median household income, unless the debtor requests a longer commitment period (Source 1).
- Five-Year Plan (60 Months): Required when the debtor's CMI exceeds the state median household income (Source 1). Federal law prohibits plans from extending beyond 60 months (Source 1).
Under Chapter 13 plan rules, debt claims are categorized and paid according to statutory hierarchies:
- Priority Claims: Must be paid in full under the plan. These include bankruptcy administrative costs, court fees, employee wage claims up to statutory limits, tax debts, and domestic support obligations (Source 1).
- Secured Claims: Claims backed by collateral (mortgages, auto loans). To retain the collateral, the plan must provide for full payment of ongoing installments plus curing past arrearages (Source 1).
- General Unsecured Claims: Credit cards, personal loans, and medical balances. These claims receive any remaining disposable income over the plan duration; partial payment is acceptable as long as it meets the liquidation test threshold (Source 1).
Impact on Secured vs. Unsecured Debts and Discharge Limits
The final goal of filing bankruptcy is obtaining an order of discharge, which releases the debtor from personal liability for covered debts and permanently enjoins creditors from taking collection action (Source 1, Source 3). However, the scope of discharge varies between Chapter 7 and Chapter 13, and certain obligations cannot be erased under federal law (Source 1).
Secured debts carry a lien on real or personal property (Source 1). While a bankruptcy discharge eliminates personal liability on a secured note, it does not automatically remove the underlying lien (Source 1). If a debtor defaults on secured payments in Chapter 7, the creditor may seek court permission to repossess or foreclose on the collateral (Source 1). In Chapter 13, debtors maintain lien survival protections by curing defaults within the plan (Source 1).
Certain types of unsecured liabilities are explicitly designated as non-dischargeable under Section 523 of the Bankruptcy Code (Source 1). These obligations remain fully enforceable regardless of filing Chapter 7 or completing a Chapter 13 plan:
- Domestic Support Obligations: Child support, alimony, and marital maintenance obligations (Source 1).
- Certain Tax Liabilities: Unfiled tax returns, fraudulent returns, or recent income tax obligations (Source 1).
- Educational Loans: Most government and private student loans, unless the debtor successfully demonstrates 'undue hardship' in a separate adversary proceeding (Source 1).
- Court Fines and Penalties: Criminal fines, restitution orders, and statutory penalties owed to governmental units (Source 1).
- Debts Incurred Through Fraud: Liabilities arising from false pretenses, embezzlement, or intentional torts (Source 1).
Filing Bankruptcy Costs, Legal Fees, and Administrative Process
Initiating a bankruptcy case requires adhering to specific administrative prerequisites and paying court fee schedules established by the federal judiciary (Source 1, Source 3). Standard statutory filing fees apply nationwide across bankruptcy courts (Source 1).
- Statutory Filing Fees: Court fee schedules set uniform filing costs for Chapter 7 and Chapter 13 petitions (Source 1). Individuals earning below specific poverty guidelines may apply to pay Chapter 7 filing fees in installments or request a fee waiver from the court (Source 1).
- Mandatory Credit Counseling: Prior to filing, debtors must complete a mandatory credit counseling briefing from an agency approved by the U.S. Trustee Program (Source 1, Source 3).
- Debtor Education Course: After filing but before receiving a discharge, debtors must complete an approved personal financial management instructional course (Source 1, Source 3).
Legal fees vary based on local fee structures, case complexity, and the chosen chapter (Source 1). In Chapter 7 cases, legal fees are generally paid upfront prior to filing because post-petition legal fees are subject to discharge rules (Source 1). In Chapter 13 cases, courts often permit attorney fees to be partially bundled into the monthly repayment plan, reducing initial out-of-pocket costs at filing (Source 1).
What happens if a debtor's income is above the state median?
If income exceeds the state median, the debtor must perform the second step of the means test calculation (Source 2). This involves deducting allowed expenses based on IRS standard allowances, payroll deductions, and secured debt payments to determine disposable income (Source 2). If net disposable income is below federal statutory limits, the debtor can still qualify for Chapter 7 (Source 2). Otherwise, the debtor must utilize Chapter 13 (Source 1, Source 2).
Can a home be lost during Chapter 7 bankruptcy?
A home can be sold by a Chapter 7 trustee if the home's equity exceeds the applicable state or federal homestead exemption limit and outstanding mortgage liens (Source 1). If equity is fully exempt, the trustee cannot sell the home; however, the debtor must remain current on ongoing mortgage payments to avoid foreclosure by the lender (Source 1).
How long do Chapter 7 and Chapter 13 records remain on credit reports?
Under federal credit reporting rules, a Chapter 7 bankruptcy filing may remain on a credit report for up to 10 years from the filing date (Source 3). A Chapter 13 filing typically remains on credit bureau records for up to 7 years from the date the petition was filed (Source 3).
Sources
- Bankruptcy Basics — Administrative Office of the U.S. Courts
- Means Testing Information — U.S. Department of Justice - Executive Office for United States Trustees
- What is Bankruptcy? — Consumer Financial Protection Bureau
This article is for general information only and is not professional advice. Figures come from public sources and change over time; check the official source before you act.
More from True Money Net
- Save Up to 50 Percent on Dental Implants at Local Schools
- See 5 Essential Rules to Qualify for Free Implants
- Find 5 Official Low Cost Dental Programs for Seniors Today
- 5 Hidden Rules to Get Dental Implants Covered by Insurance
- SSDI Spousal Benefits: Eligibility Rules, Payment Limits, and Calculations
- FHA 203(k) Home Rehabilitation Loans: Appraisal Guidelines, Eligible Upgrades, and Fee Structures